Raymond Realty reports a healthy Q2FY27 performance
Oct 28, 2026
VMPL
Mumbai (Maharashtra) [India], October 28: Raymond Realty Limited today announced its unaudited financial results for the quarter ended 30th September 2026.
KEY HIGHLIGHTS
* Strong Booking Value Trajectory: Q2 FY27 Booking Value up 98% YoY to ₹902 Cr; H1 FY27 Booking Value up 111% to ₹1,602 Cr
* Booking Value Contribution Mix: Mumbai JDAs - 57% : Owned Thane Land Parcel - 43%
* Robust Customer Collections: Q2 FY27 Collections up 67% YoY to ₹ 682 Cr; H1 FY27 Collections up 57% YoY to ₹1233 Cr
* Strong Growth Visibility: Total portfolio is now ~ ₹52,000 Cr in Gross Development Value (GDV), with a prudent mix of Own thane land as well as Mumbai JDA projects
* Total Income of ₹ 757 Cr in Q2FY27 vs ₹ 706 Cr in Q2FY26, 7% Y-o-Y growth
* EBITDA of ₹ 115 Cr in Q2FY27 vs ₹ 101 Cr in Q2FY26, 14% Y-o-Y growth
* Net Debt of ₹ 912 Cr, Debt to Equity ratio of 0.8x, well below the ceiling of 1.0x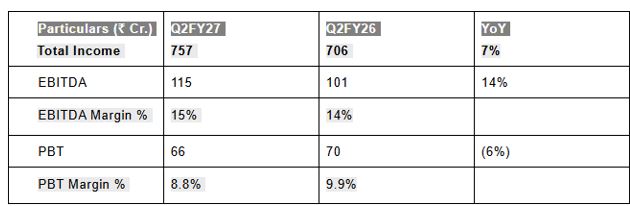
Raymond Realty delivered a strong financial performance in Q2 FY27, recording a Total Income of ₹757 Crore, representing a steady 7% year-on-year growth. Notably, this growth was achieved with no new project launches during the quarter, driven entirely by sustained sales velocity and steady price realization within the existing "Address by GS" portfolio. Driven by an optimized product mix, EBITDA rose 14% year-on-year to ₹115 Crore, with margins expanding to 15%. While margins naturally fluctuate by project phase due to upfront marketing and construction setup costs, they are expected to normalize progressively, keeping the company firmly on track to meet its FY27 EBITDA margin guidance of 17%–19%. Moving forward, operational growth will be accelerated by a robust upcoming launch pipeline in the Mumbai Metropolitan Region (MMR) representing a cumulative Gross Development Value (GDV) of over ₹4,100 crore.
Strategic Portfolio & Operational Review
Our Current Total portfolio is now ~ ₹52,000 Crore in Gross Development Value (GDV), reflecting a diversified and high-growth asset base across the MMR.
100 Acre Thane Land Parcel: Cornerstone of our success, with a ~ ₹25,000 Crore revenue potential.
* Development Velocity: Approximately 65 acres are currently under development, representing ~6.7 million sq. ft. of RERA carpet area and a revenue potential of ~ ₹16,500 Crore
* Sales Milestones: Performance remains robust with ~ ₹9,770 Crore already sold and collections reaching ~ ₹7,977 Crore to date
* Completed Projects: During Q2 FY27, OC received for Address by GS Season 1 Tower B in Thane comprising of 270 units, Total RERA Carpet Area of 3,44,478 sq. ft., well ahead of RERA Timelines (Proposed RERA Completion Date was Mar-28).
JDA Portfolio: The Structural Pivot to Asset-Light Growth, which now comprises eight projects with a combined revenue potential of ~ ₹27,000 Crore.
* Development Velocity: 4 JDA projects have been launched in Bandra, BKC, Wadala and Sion, representing ~ 2.8 million sq. ft. of RERA carpet area and a revenue potential of ~ ₹11,500 Crore. These marquee developments are the flagship pillars of our JDA portfolio and a testament to our ability to scale with speed and sophistication.
* Sales Milestone: Performance remains strong with ~ ₹3,430 Crore already sold and collections reaching ~ ₹857 Crore to date
* New Planned Launches: We are accelerating our growth trajectory over the next two quarters with a strong pipeline of MMR launches, representing a cumulative GDV of over ₹4,100 crore. The current financial year will feature two premier JDA project launches: 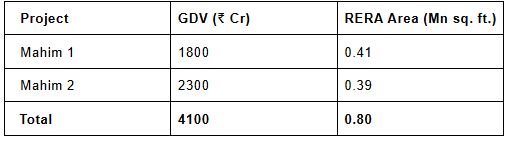
Leverage & Liquidity
* Prudent Leverage: Maintaining a healthy balance sheet, we concluded the quarter with a Gross debt of ₹1,220 Crore and Net Debt of ₹912 Crore and a debt / equity ratio of 0.8x comfortably below our 1.0x ceiling, providing headroom for future expansion.
* Liquidity & Cost of Debt: With a ₹308 Crore liquidity buffer, we are fully funded for the next year of construction spends. Our Cost of Debt remains stable at ~9.60%.
* Interest Cost: Total Interest Cost for Q2 FY27 is ₹44 Crore which includes Interest on Bank Borrowings of ~₹27 Crore and ~₹17 Crore is towards Interest to Government authorities: BMC/TMC / MHADA for Additional FSI and Approvals.
* Credit rating Update:CARE reaffirmed Raymond Realty at CARE A+ with a Stable outlook, citing consistent booking momentum, an improving launch pipeline and healthy execution on the existing portfolio.
* FY27 guidance Update: Raymond Realty remains on track for ~20% growth in pre-sales, ROCE of ~20%, EBITDA margin of 17–19% and PAT margin of 9–10%.
Commenting on the performance, Mr. Harmohan Sahni, Managing Director & CEO, Raymond Realty Limited said;” Guided by our 'Go Beyond' ethos, we carry forward the scaled execution and strategic clarity that defined our success last year into H1 FY27. Our performance during this period reflects strong operational momentum, validating our execution capabilities and the deep trust homebuyers place in us. Nearly doubling our quarterly pre-sales without new launches, alongside a 67% surge in collections, highlights our intense focus on operational and cash flow efficiency. Delivering a key Thane tower 18 months ahead of its RERA timeline stands as a strong testament to our construction capabilities. With a disciplined capital approach and a ₹4,100+ crore MMR launch pipeline ahead, we are well-positioned to achieve our full-year growth guidance and compound returns for our shareholders."
(ADVERTORIAL DISCLAIMER: The above press release has been provided by VMPL. ANI will not be responsible in any way for the content of the same.)